There are a lot of discussions about the best way to deal with the Social Security shortfall, currently projected to occur in the fourth quarter of 2032 for the Old-Age and Survivors Insurance (OASI) Trust Fund. At that time, if nothing is done, Social Security will have enough incoming revenue to pay approximately 78% of scheduled retirement and survivor benefits.
What’s not discussed is that the percentage is projected to continue declining, dropping by an average of about ¼ of a percentage point per year. By 2100, it’s projected to be approximately 62%.
One of the options is to “uncap” Social Security. Currently, only the first $184,500 of covered earnings is subject to Social Security payroll taxes. In 2027, that moves to $192,300. Surprisingly, taking the cap off won’t get us all the way there, but it’s an option to get closer. It’s also a favorite go-to in the debate over how to fix Social Security.
So we thought we’d run the numbers on LeBron James, assuming the earnings cap is eliminated entirely and all additional covered earnings (earnings where Social Security tax is collected) use the existing Social Security benefit formula.
What If LeBron James Had No Social Security Earnings Cap?
LeBron’s estimated current annual compensation is:
| Compensation Source | Annual Amount |
|---|---|
| NBA Salary | $3.88 million |
| Estimated Endorsements and Other Income | ~$91 million |
| Total | Approximately $95 million |
For purposes of this illustration, we’re making three assumptions. First, the Social Security earnings cap is removed beginning in 2027. Second, all $95 million of LeBron’s estimated annual compensation qualifies as Social Security-covered earnings. Third, LeBron receives full benefit credit for those additional earnings under the existing Social Security benefit formula.
We’re also assuming his annual compensation remains at $95 million for the next 25 years. On the face of it, this seems unlikely, but the earning potential of a top NBA player can extend well beyond their playing years. Given his estimated $1.4 billion net worth, according to Forbes, much of which is invested privately, this number looks less distant.
Michael Jordan, for example, was worth an estimated $400 million in April 2003, when he retired for the final time, and is currently estimated to have a net worth of $4.7 billion. So LeBron’s annual income could actually be significantly more than $95 million. Of course, income generated from investments would not ordinarily count toward Social Security benefits, but we’re taking the cap off, so lets take it all the way off!
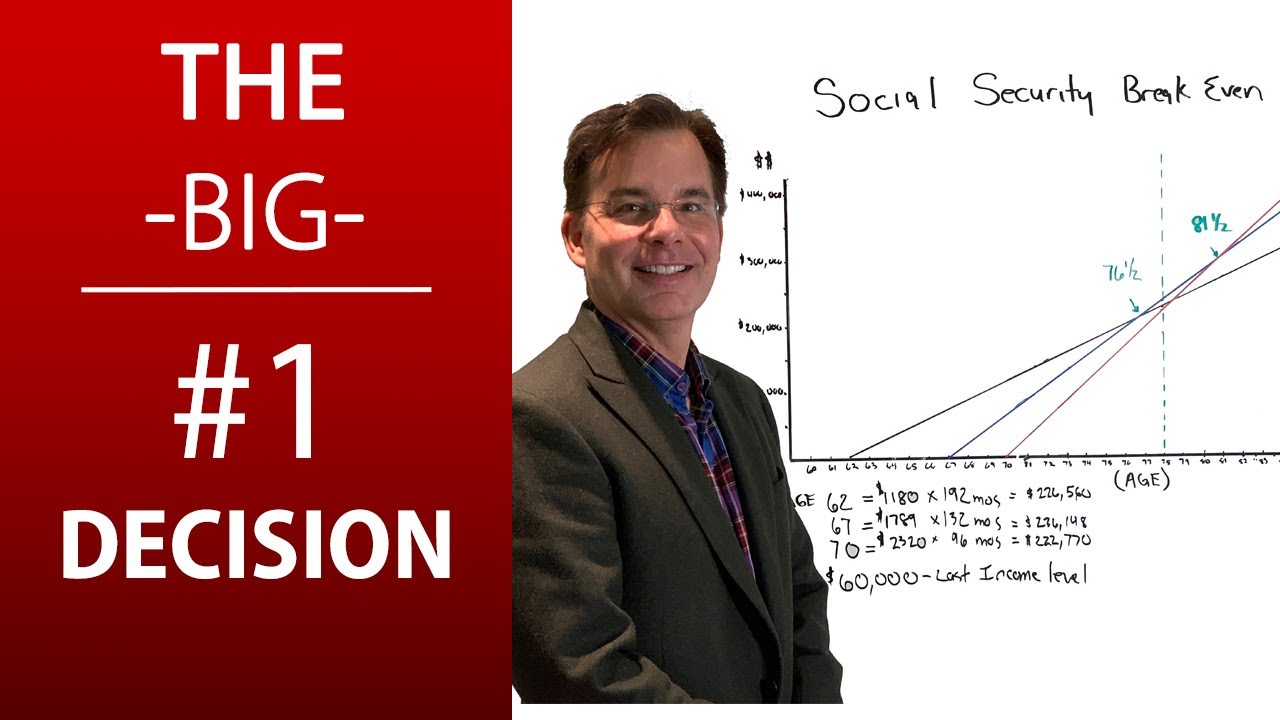
Let’s also not get greedy, we’ll stick with $95 million per year for the next 25 years, despite his $1.4 billion (and growing) net worth. LeBron will be 42 in December, which means his full retirement age is 67. We’ll assume he waits until then to claim. If he waited until age 70, his benefit would be approximately 24% higher. If he claimed at age 62, it would be 30% lower than his benefit at full retirement age.
Step 1: Calculating LeBron’s Lifetime Social Security Earnings
There are three calculations we need to make to come up with his payment. The first is to calculate his lifetime earnings, adjusted using a process called wage indexing. Social Security generally takes a worker’s highest 35 years of indexed earnings and disregards the rest.
This is important because wages have increased considerably over time. Social Security adjusts historical earnings to reflect changes in average wages, allowing earnings from different years to be compared on a more consistent basis. Fortunately, the Social Security Administration publishes the information needed to understand this process.
For our illustration, we only need to estimate LeBron’s covered earnings for the last 10 years, because we’re assuming his next 25 years will all be substantially higher. Importantly, his Social Security benefit is based on covered earnings, not necessarily everything he earns. In other words, his benefit doesn’t increase simply because his income exceeds the taxable maximum. Whether he earned $184,500 in 2026 or $95 million in 2026, he would receive Social Security credit for no more than $184,500 that year under current law.
How Social Security Adjusts Past Earnings
The Social Security taxable maximum was $184,500 in 2026. That maximum generally increases over time based on changes in national average wages. Historically, the maximum was lower, but wage indexing can bring those earlier earnings closer to the equivalent of more recent earnings.
Let me illustrate. The taxable maximum was $176,100 in 2025 and $184,500 in 2026. That represents an increase of approximately 4.77%. Social Security uses changes in the national average wage index to adjust earnings from earlier years. The farther back the earnings, generally speaking, the larger the adjustment can be.
Here is a simplified illustration using recent taxable maximums and hypothetical adjustment factors:
| Year | Earnings Cap | Illustrative Wage Adjustment Factor | Adjusted Earnings |
|---|---|---|---|
| 2023 | $160,200 | 1.142 | $182,948 |
| 2024 | $168,600 | 1.089 | $183,605 |
| 2025 | $176,100 | 1.045 | $184,025 |
| 2026 | $184,500 | 1.000 | $184,500 |
Note: These adjustment factors are illustrative, not the actual factors Social Security would use to calculate LeBron’s retirement benefit. The table is intended to demonstrate how historical earnings can be adjusted toward a common wage level.
Social Security indexes earnings through the year before a worker turns 60. Earnings beginning with the year the worker turns 60 are not wage-indexed. LeBron doesn’t turn 60 until 2044, so his actual indexing factors will depend on future changes in national average wages.
Estimating LeBron’s 35 Highest-Earning Years
To make things easy, let’s assume LeBron’s highest 35 years of indexed covered earnings consist of 10 years averaging approximately $180,000 annually and 25 years averaging $95 million annually.
We can’t go back in time and collect additional Social Security taxes for years that are already over. However, under our hypothetical reform, additional taxes could be collected beginning in 2027. His lifetime indexed covered earnings, for purposes of calculating his hypothetical Social Security benefit, would therefore be:
($180,000 × 10) + ($95,000,000 × 25)
$1,800,000 + $2,375,000,000 = $2,376,800,000
His lifetime indexed covered earnings would be approximately $2.377 billion.
It’s important to remember that even though LeBron earned more than $180,000 per year in the past, he cannot receive additional Social Security benefit credit for earnings above the taxable maximum in those years. Our hypothetical reform begins in 2027 and does not retroactively change his earlier covered earnings.
Why We’re Using 2026 Dollars
We’re expressing everything in 2026 dollars. LeBron’s actual retirement benefit in 2051, when he reaches full retirement age, would be calculated using the benefit formula and indexing rules applicable to him at that time. His payment would likely be significantly higher in nominal dollars, assuming wages and prices continue increasing between now and 2051.
Still, the best we can do for this illustration is express everything in 2026 dollars because we don’t know what future wage growth or inflation rates will be. This is a simplified hypothetical calculation, not a projection of LeBron’s actual Social Security benefit. His actual benefit would depend on future earnings, the applicable indexing factors, and the law in effect when he becomes eligible.
I digress.
Step 2: Calculating LeBron’s Average Indexed Monthly Earnings (AIME)
The next step is to take LeBron’s lifetime indexed covered earnings and turn them into what’s called average indexed monthly earnings, or AIME. This represents the monthly average of his highest 35 years of indexed earnings.
The calculation is surprisingly simple. There are 420 months in 35 years, so we divide $2.3768 billion by 420:
$2,376,800,000 ÷ 420 = $5,659,047.62
Social Security rounds AIME down to the next lower whole dollar. That gives LeBron a hypothetical AIME of $5,659,047 per month.
Is this LeBron’s Social Security payment at full retirement age? No. We need to feed that number into a special formula that uses what Social Security calls bend points.
Step 3: Applying Social Security’s Bend Points
Bend points effectively haircut those numbers because, at its core, Social Security is designed to provide proportionately greater income replacement for lower earners. Those who earned a modest income, in many cases, will get back more than they contributed. Those who earned a very high income generally receive a much smaller percentage of their average earnings as benefits.
In 2026, Social Security uses the following percentages to calculate a worker’s primary insurance amount, or PIA:
| Portion of Average Indexed Monthly Earnings | Benefit Percentage |
|---|---|
| First $1,286 | 90% |
| Between $1,286 and $7,749 | 32% |
| Above $7,749 | 15% |
These are the 2026 bend points. We’re applying them to LeBron’s hypothetical AIME to illustrate what his benefit would look like under today’s formula.
First Bend Point: 90%
LeBron would receive 90% of the first $1,286:
$1,286 × 90% = $1,157.40
Second Bend Point: 32%
He would also receive 32% of the difference between $7,749 and $1,286:
$7,749 − $1,286 = $6,463
$6,463 × 32% = $2,068.16
Third Bend Point: 15%
What about the remaining $5,651,298? He would receive 15% of that amount:
$5,651,298 × 15% = $847,694.70
The Result: LeBron’s Hypothetical Social Security Benefit
Adding those three amounts together:
| Benefit Calculation | Monthly Amount |
|---|---|
| First bend point (90%) | $1,157.40 |
| Second bend point (32%) | $2,068.16 |
| Third bend point (15%) | $847,694.70 |
| Total Before Rounding | $850,920.26 |
Social Security rounds the primary insurance amount down to the next lower dime. That produces a hypothetical benefit of $850,920.20 per month, or approximately $10.21 million per year.
That’s an extraordinary amount of money, but there’s another side to the calculation. To understand the full implications of eliminating the Social Security earnings cap, we also need to examine how much LeBron and his employers would contribute to the system.
How Much Would LeBron Contribute to Social Security?
Under current law, Social Security payroll taxes are generally 6.2% for employees and 6.2% for employers. Combined, that’s 12.4%.
If the taxable earnings cap disappeared and all $95 million of LeBron’s annual compensation became subject to Social Security payroll taxes, the combined annual contribution would be:
$95,000,000 × 12.4% = $11,780,000
That’s approximately $11.78 million per year. Over 25 years, the total would be:
$11,780,000 × 25 = $294,500,000
In other words, under our assumptions, LeBron and his employers would contribute approximately $294.5 million to Social Security over those 25 years alone.
That doesn’t include the Social Security taxes paid on his covered earnings during his earlier working years. Calculating those historical contributions would require using his actual covered earnings and the payroll tax rules applicable in each year, rather than his wage-indexed earnings.
The $294.5 million figure also assumes the combined Social Security payroll tax rate remains at 12.4% throughout the hypothetical 25-year period.
What Does This Tell Us About Removing the Social Security Earnings Cap?
Under our hypothetical assumptions, LeBron James could receive approximately $850,920 per month, or $10.21 million annually, in Social Security retirement benefits. At the same time, he and his employers would contribute approximately $294.5 million over the 25 years leading up to retirement.
The important distinction is that this outcome depends on how Congress removes the earnings cap. If lawmakers eliminate the cap and continue providing full benefit credit for all additional covered earnings, extremely high earners could qualify for extraordinarily large Social Security benefits.
But if lawmakers remove the cap for taxation without providing additional benefit credit, the outcome would be very different. And if lawmakers introduce a new, lower benefit percentage for earnings above the current taxable maximum, the result would fall somewhere between those two approaches.
That’s why simply saying we should “uncap Social Security” doesn’t tell us everything we need to know.
The question isn’t just how much additional tax revenue Social Security would collect. It’s also how much of that money would eventually be returned to high earners through additional benefits.
Footnote: Assumptions and Methodology
This illustration uses the 2026 Social Security benefit formula, expressed in 2026 dollars. It assumes that beginning in 2027, the taxable earnings cap is eliminated, all $95 million of LeBron James’s annual income qualifies as Social Security-covered earnings, and those earnings receive full benefit credit under the existing formula. The historical wage-indexing figures are illustrative. Actual benefits would depend on future wage indexing, applicable benefit formulas, and changes in Social Security law. The figures are hypothetical and are not a projection of LeBron James’s actual retirement benefits.